From the founder of Carry and Teachable

The tax code has a second set of rules for people who earn well. Nobody hands them to you.

Pay Less in Taxes is every one of those rules in 38 short video lessons, with the software that puts each one in place for you.

Ankur in his studioWatch, with sound
Why people who earn well overpayAnd what actually fixes it10:01
Join for $499 a year
Money back if it doesn’t find you what you paid in 30 daysOne payment, nothing renews
Ankur and his companies inForbesMorning BrewTechCrunchTBPN
38

Short video lessonsFour to eight minutes each, in sections by who you are. You only see yours.

35

Lessons that end in a toolReimburse opens on your own numbers and does what the lesson taught.

29

Tools and trackersBuilt for this, so no lesson ends in “now go figure it out”.

Sound familiar?

You earn well. You still write a big check every April.

Your accountant files every year and has never once called you in October.
You’ve heard of the backdoor Roth. It still isn’t done.
You have cash in a savings account and no idea what it costs you in tax.
You meant to max out the HSA last year. And the year before.
Your RSUs vested, and April’s bill was a surprise.
Every “pay less tax” video online is either for someone earning a third of what you do, or a guy telling you to buy a jet.
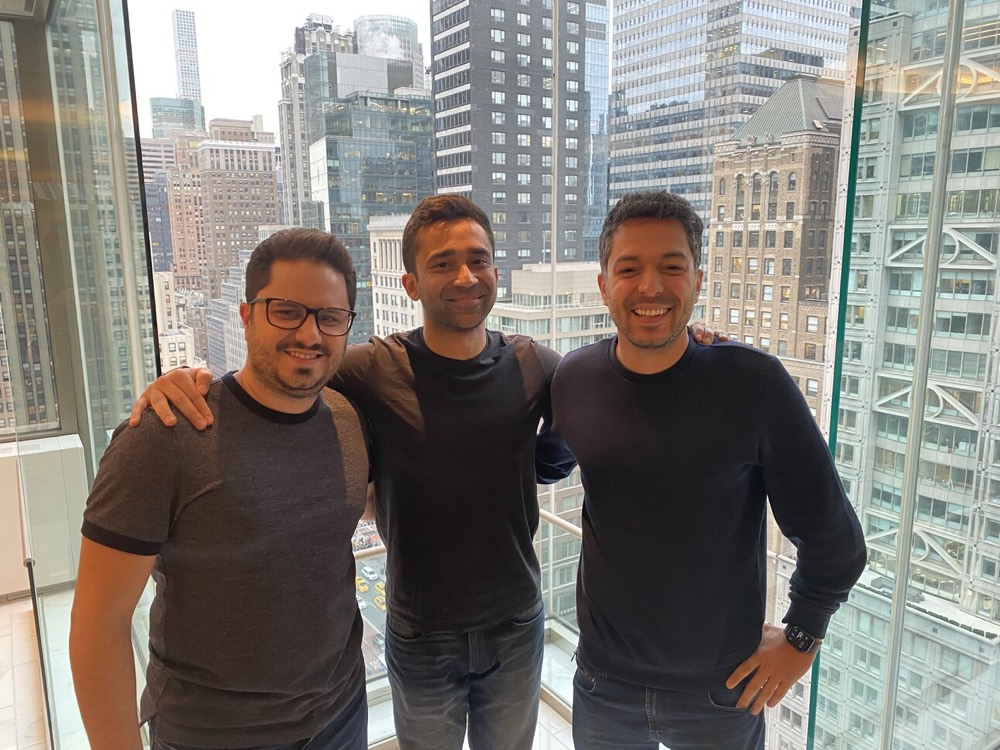
Sale dayAnkur and two colleagues by a window above Midtown Manhattan
March 12, 2020, minutes after signing the sale of Teachable.
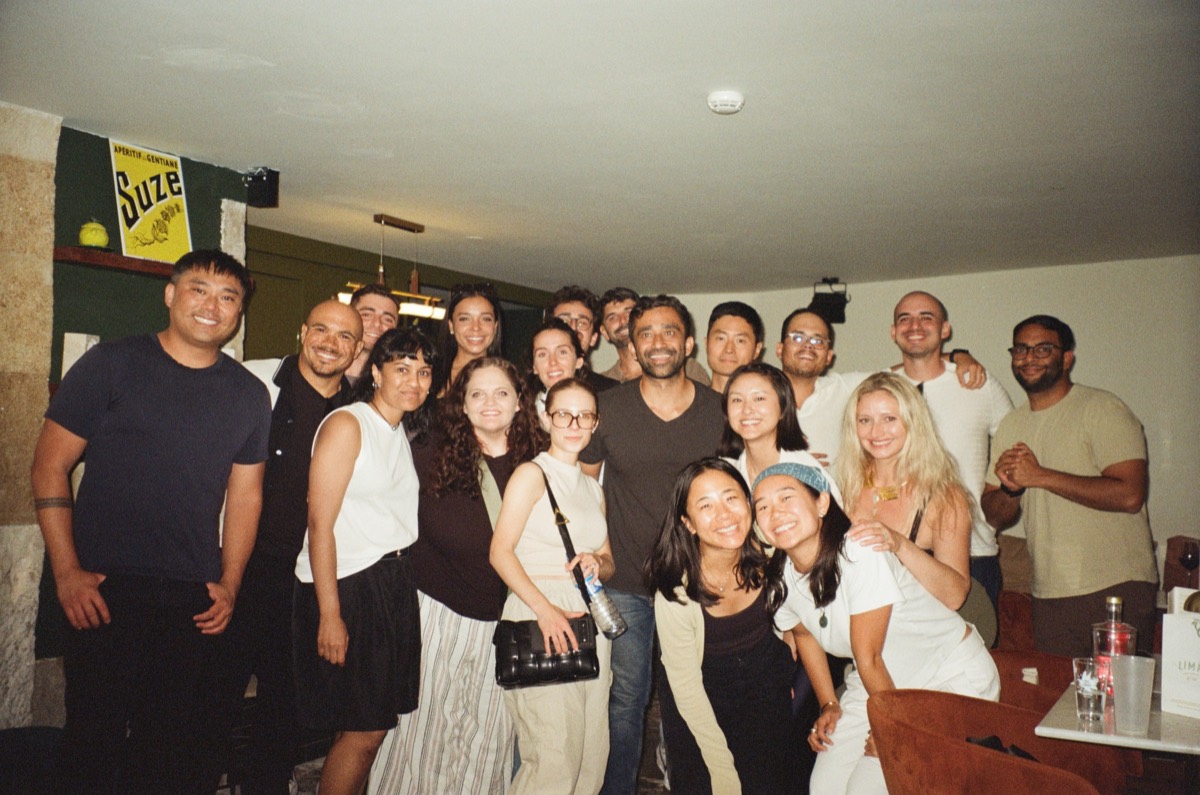
Ankur in the middle of the Carry team in Lisbon
The Carry team in Lisbon. Carry helped business owners and high earners pay less in taxes.

Hi, I’m Ankur.

I found out how little I knew about taxes two months before it was too late.

On April 20, 2020, a single wire hit my bank account for an amount I genuinely couldn’t process. I had just turned 31. I’d sold Teachable, the company I’d spent seven years on, and I hadn’t the slightest clue what to do with any of it.

What I had done, barely in time, was learn about something called QSBS. It lets founders and early employees of some startups sell their shares without paying federal tax on the gain, up to a limit. To me it felt like black magic.

I found out about it about two months before the sale. I hired expensive lawyers and accountants, and we used it three times: my own shares, a trust for my future family, and a charitable trust that pays me for 20 years. Two months later and none of that would have been possible, because the trusts had to own the shares before the sale.

It still left me with a hefty tax bill, and honestly I was fine with that. I should pay taxes on this. I’ve clearly gotten a lot of services from the government.

But the difference between paying what the law asks and paying a lot more wasn’t how smart I was. It was whether someone told me in time.

So in 2022 I started Carry, to help business owners and high earners pay less in taxes: Solo 401(k)s, the mega backdoor Roth, the accounts most people have never heard of. Running it, I talked to thousands of people about their taxes, and almost everyone was overpaying by a lot.

Pay Less in Taxes is everything I learned, on both sides of that table.
“Tax strategy is real alpha. I believe that deeply.”

Ankur, who keeps most of his money in index funds because he sucks at picking stocks
“Ankur’s the man! He will teach you money tips nobody really teaches you. I could talk to him about anything but I want him to teach me about taxes.”
Shaan PuriHost, My First Million
“My go-to resource on anything personal finance and taxes.”
Nick TalaricoFounder, Super Free Games
“Ankur puts out really good content. He’s one of my top three follows on X. Just very tactical and practical.”
Alex HormoziFounder, Acquisition.com

These aren’t loopholes

Congress wrote them on purpose. And they’re worth more the more you earn.

The tax code is a list of things the government wants you to do: save for retirement, pay for your own health care, give to charity, start companies, own a home. Each one comes with a break, and each break comes with a limit, a deadline and a form.

What $1 into your 401(k) is worth in tax this year

12% bracket12¢
24% bracket24¢
35%, in California44¢
Top bracket, New York City52¢

2026 federal brackets for a single filer, with California at $300,000 and New York State and City at $1,000,000. Illustrative.

So why doesn’t everyone do this?

It’s the April problem.

The only person who looks at your whole tax year is your accountant, and they look at it after it’s over. Your employer sees your paycheck, your brokerage sees your trades, HR sees your 401(k). Nobody sees all of it while you can still change it.

Jan 2026
Jan 2027
Apr 15
Dec 1

Last chance to raise your 401(k) at payroll

Dec 31

Gifts, harvested losses, a Roth conversion

Apr 15

IRA, HSA, and it’s too late for the rest

Your accountant looks here

February to April, after the year is over

On top of the April problem

Three things almost everyone believes. I believed all three.

Belief 1

“My accountant handles this.”

Your accountant handles filing. Planning is a different job, and most of it has to happen before December 31, months before you send them anything.

Belief 2

“This is for the very rich.”

QSBS is. Most of the rest isn’t. The backdoor Roth exists because a single person earning over $153,000 can’t use a Roth IRA the normal way. That’s a lot of people with a paycheck.

Belief 3

“I’ll get to it.”

This is the expensive one. Every move has a deadline, and the deadlines don’t care that you meant to. I was two months from missing mine.

Why this isn’t just another course

I built a course platform, then a tax company. This is both.

At Teachable I watched what happens after people buy courses: most static courses are bought and forgotten. This one is interactive, built to actually save you money on taxes. Knowing about the backdoor Roth doesn’t open an IRA, fill in Form 8606 or remind you in April. So every lesson here ends in Reimburse, the software that does what it taught.

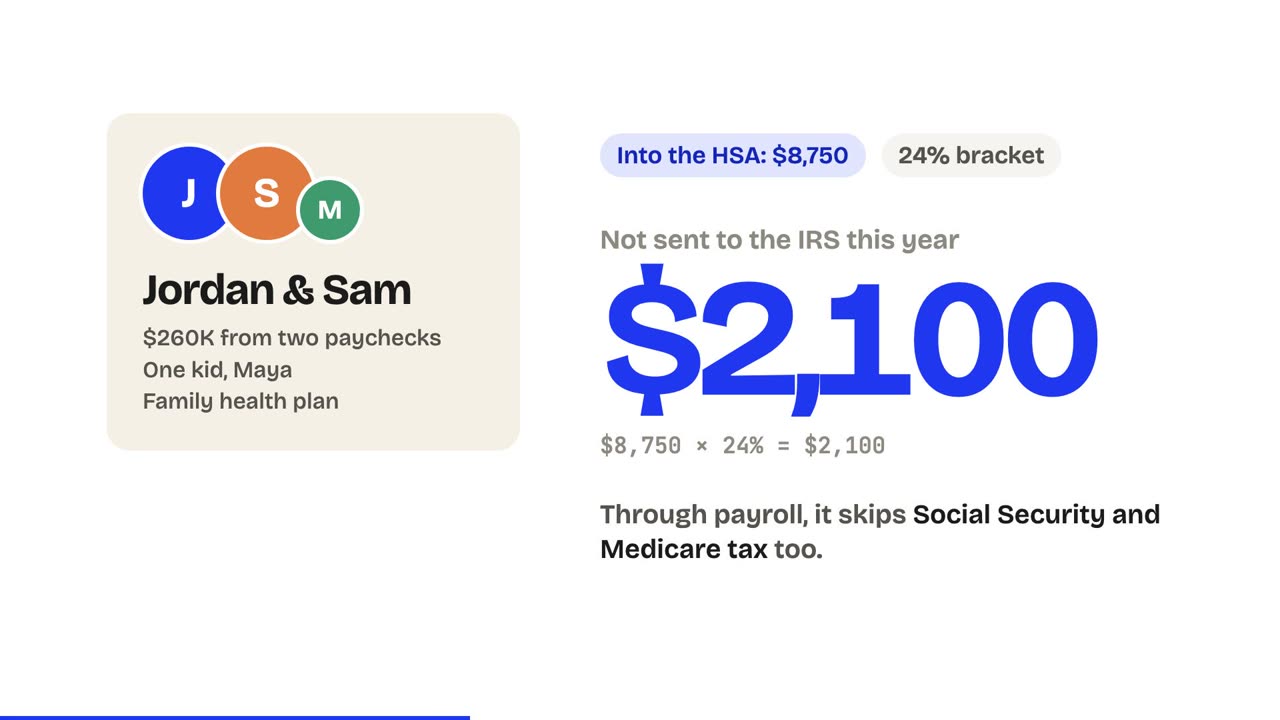
A lesson frame: Jordan and Sam put the family limit into the HSA
Step 1

Watch it

A short lesson on one strategy, worked out on a real household. Every figure is dated and sourced on screen.

Fill the HSA$8,750 for the family, by April 15.$2,100 back
Backdoor Roth, bothAfter the old IRA is empty.Tax-free later
Raise your 401(k)Tell payroll by December 1.On your year
Step 2

Do it

The lesson opens Reimburse on your own numbers. Each move is priced on your whole return, and one tap puts it in your plan.

15
APR 2027
Last day for 2026’s HSAAn email 14 days before, and again 2 days before.
Step 3

Don’t miss it

Its deadline lands on your calendar. Every December, one email lists what in your plan isn’t done yet.

The technology

Your whole tax year, worked out while you can still change it.

The same engine runs every page: Form 1040 in order, all fifty states, checked against an open tax model on 5,000 households.

2025 FORM 1040
READ IN 40 SECONDS
Wages, line 1a$185,000
Business income, Sch. C$142,300
Capital loss carryover-$3,000
QBI deduction-$24,860
TAX$71,410
Upload

Your return, read

Drop in last year’s return, a transcript, a pay stub or a brokerage statement. Every schedule is read and you check the lines. The file isn’t kept, only the numbers.

What if I put $20,000 into a Solo 401(k)?

Your 2026 tax comes down by $7,120, and you’d still meet the safe harbor with your January payment.

Fill a Solo 401(k)Try it on your year, or add it to your plan.$7,120 back
Ask

Ask, with your numbers

Ask anything about your own taxes. The answer runs your actual year through the engine, so every number in it is one the pages would show.

As it stands$86,400
With your plan$79,280
With every move$71,950
Model

What if, on whole returns

Your year as it stands, with your plan, with every move, or with any change you type, side by side. A raise, a sale, a move to another state.

Left to pay for 2026$31,240Pay $12,000 by January 15 and there’s no penalty.
Forecast

Your year, before it’s over

Add your latest pay stub and see what you’ll owe in April, what’s already withheld, and the payment that keeps you clear of a penalty.

Figures on these cards are an example household, not yours.

Proof, from my own accounts

I do every one of these myself. Here’s what they did for me.

Tax-loss harvesting, 2026

$324,628

of losses harvested in my direct indexing account

Short-term net losses$327,285
Long-term net losses$0
Off my taxes, by Frec’s estimate$160,042

From my account, October 2026.

The mega backdoor Roth

$72,000

into my Solo 401(k) this year, the most it takes

After-tax, converted to Roth$47,500
Pre-tax, as the employee$24,500

Silly Money, March 2026.

Where I park cash

$4,726

one month’s dividend, January 5, 2026

FundVYFXX
What it holdsNew York municipal bonds
Federal, state and city tax on it$0

Posted January 7, 2026.

My own accounts, as I posted them; my income, portfolio and state aren’t yours, and your results will be different. I am an investor in and adviser to Frec, a direct indexing provider. Carry’s Solo 401(k) platform is run today by Lettuce Financial, where I hold the title of strategic adviser.

Try it, 30 seconds

What would apply to you?

Household income
Filing
Where you live
Which of these are true for you?

Up to, this year

$14,137

The most 4 moves could put back this year, at about 33¢ on the dollar, your top rate.

Raise your 401(k) to $24,500Lesson 6. If none of it is in yet.$8,158 back
A dependent care FSALesson 5. $7,500 of daycare or camp, paid before tax.$2,674 back
Fill your HSALesson 7. $8,750 for a family, through payroll, and keep the receipts.$2,306 back
Harvest losses all yearLesson 14. $3,000 a year off your pay, and losses against your gains.$999 back
The backdoor Roth, both of youLesson 8. Past the Roth IRA’s income line.Tax-free later
The mega backdoor RothLesson 9. If your plan takes after-tax money.Tax-free later
Kids’ accountsLesson 28. The 529, a Trump Account, a Roth for kids.Tax-free later
Keep your home’s receiptsLesson 29. Every improvement raises what you can sell for tax-free.On record

Illustrative, from a few answers and your top rate, assuming none of these is done yet. Not tax advice.

No secrets behind the paywall

Here’s one strategy, in full.

Say you’re single, you live in New York City, you earn $300,000, and you keep $150,000 in a savings account paying 4.00%. That interest is taxed by Washington, Albany and the city, plus the 3.8% tax on investment income: about 53% in all.

Move it to a money market fund that holds only US Treasuries, paying 3.90%. It pays less, but no state or city can tax interest from Treasuries.

That’s $784 more a year, for moving money once.

Most of the course isn’t one big trick. It’s ten of these, every year, compounding. This one you can check for free right now with our tax-equivalent yield calculator.

Illustrative. Yields change daily, and New York, California and Connecticut only exempt a fund with at least half its assets in US obligations.

SAVINGS ACCOUNT
$150,000 AT 4.00%
Interest$6,000
Federal and investment income-$2,328
New York State and City-$876
YOU KEEP$2,796
+$784 a year
TREASURY MONEY MARKET
$150,000 AT 3.90%
Interest$5,850
Federal and investment income-$2,270
New York State and City$0
YOU KEEP$3,580

The syllabus

38 lessons in 7 sections. You see only yours.

A frame from the HSA lesson3:38
Free lesson

The HSA, the only account that’s never taxed

Jordan and Sam put $8,750 in and keep $2,100 from the IRS this year, and the money can grow untaxed for decades. Watch it at the top of this page before you decide.

01Start here5 lessons, for everyone
▶
Welcome
Do it in Reimburse: Build your course
01
How taxes work
Do it in Reimburse: Your 2026 forecast
02
What’s new in 2026New in 2026
Do it in Reimburse: What if, on your own year
03
Where your next dollar goes
Do it in Reimburse: Savings waterfall
04
Your deadlines and December 31
Do it in Reimburse: Your calendar
02A paycheck6 lessons, for a paycheck
05
Your employer benefits, decoded
Do it in Reimburse: Benefits checker
06
The 401(k): match, limits and true-up
Do it in Reimburse: Ways to save
07
The HSA
Do it in Reimburse: HSA receipts
Free lesson
08
The backdoor Roth
Do it in Reimburse: Backdoor Roth check
09
The mega backdoor Roth
Do it in Reimburse: Mega backdoor checker
10
RSUs, ESPP and options
Do it in Reimburse: Equity planner
03Investing7 lessons, for anyone who saves
11
Where to park cash
Do it in Reimburse: Money market funds
12
Which account holds what
Do it in Reimburse: Placement checker
13
Capital gains and the 0% bracket
Do it in Reimburse: Capital gains
14
Tax-loss harvesting
Do it in Reimburse: Capital gains
15
Direct indexing and concentrated stock
Do it in Reimburse: A direct indexing account
Partner bonus
16
Roth conversions
Do it in Reimburse: Roth conversion planner
17
Taking money out in retirement
Do it in Reimburse: Withdrawal planner
04Work for yourself8 lessons, for anyone who works for themselves
19
Your tax rate
Do it in Reimburse: Your rate
20
Expenses, mileage and the home office
Do it in Reimburse: Business expenses
21
The Solo 401(k) and cash balance plans
Do it in Reimburse: Solo 401(k)
22
Health insurance when you work for yourself
Do it in Reimburse: Your premium credit, in the forecast
23
The S corporation, with PTET
Do it in Reimburse: S-corp calculator
24
QBI
Do it in Reimburse: Your 2026 forecast
25
Hiring your kids
Do it in Reimburse: Kids’ pay
37
Paying yourself back: the accountable plan
Do it in Reimburse: Monthly reimbursement report
05Family and home4 lessons, for parents, owners and givers
18
Giving
Do it in Reimburse: Giving planner
28
Kids: the 529, Trump Accounts and more
Do it in Reimburse: Kids’ accounts
29
Selling your home
Do it in Reimburse: Home improvements
30
Real estate and depreciation
Do it in Reimburse: Rentals and real estate hours
06Special situations3 lessons, for founders, movers and expats
32
Founders: QSBS and selling a company
Do it in Reimburse: QSBS checker
33
Moving states
Do it in Reimburse: Days tracker
34
Living abroad
Do it in Reimburse: Days tracker
07Every year5 lessons, for everyone, every year
26
Quarterly estimates
Do it in Reimburse: Your forecast and payments
27
The self-employed checklist
Do it in Reimburse: Your plan
31
Trusts and estates
Do it in Reimburse: Your estate
35
Avoiding IRS mistakes
Do it in Reimburse: Last year’s return, checked
36
The $100M Roth
A story about the most powerful account in America.
A story

Everything that comes with it

29 tools and trackers. Every lesson ends in one.

Each one opens on your own numbers, from your pay stub, your return and what you\u2019ve told it.

Your year

Your 2026 forecast

What you’ll owe in April, from your latest pay stub, worked out in Form 1040’s order, with the safe harbor.

LESSON 1 AND LESSON 24
Last year’s return, read

Upload your return or a transcript; every schedule’s lines are read in a minute, and only the numbers are kept.

Ask about your taxes

Questions about your own year, answered with your numbers by the same engine the pages use.

What if

Whole returns side by side: as it stands, with your plan, with every move, and any change you type.

Capital gains

Add a brokerage statement or sales by hand; netting, carryovers and what’s still to come.

LESSON 13 AND LESSON 14
Your calendar

Every deadline that applies to you, with an email before each one.

LESSON 4

Trackers

Business expenses

Photograph, forward or drop a receipt; it’s read, sorted to its Schedule C line and priced.

LESSON 20
Mileage

Trips at the year’s rate, from saved places.

Mixed-use bills

Phone and internet, logged each month at the work share.

HSA receipts

Every medical receipt, kept until you take the money out tax-free.

LESSON 7
Home improvements

Everything that lowers the tax when you sell, with the invoice.

LESSON 29
Charitable gifts

What counts, what’s back, and the receipts the IRS asks for.

Kids’ pay

Hours, rates and W-2s for paying your kids, kept the way an audit asks.

LESSON 25
Kids’ accounts

Each child’s 529, Trump Account and Roth, with limits and deadlines.

LESSON 28
Rental ledger

Income, expenses and depreciation by property.

Days tracker

Where you were, day by day, for a move between states or the 330-day test abroad.

LESSON 33 AND LESSON 34

Calculators and planners

Savings waterfall

Which account your next dollar goes to, and how this year’s savings divide.

LESSON 3
Money market funds

Which fund pays you most after your taxes, today.

LESSON 11
Solo 401(k)

The most you can put in, as the employee and the business.

LESSON 21
Benefits checker

Add your benefits guide; it finds the match, the HSA, ESPP and dependent care you’re not using.

LESSON 5
Backdoor Roth check

The pro-rata rule on your own IRAs, and the order to do it in.

LESSON 8
Mega backdoor checker

Whether your 401(k) takes after-tax money, and how much.

LESSON 9
Equity planner

RSU withholding, ESPP sales, ISOs and the AMT, on your year.

LESSON 10
Placement checker

Which account each investment belongs in.

LESSON 12
Roth conversion planner

How much to convert, and in which years.

LESSON 16
Withdrawal planner

The order to take money out in retirement, Social Security and RMDs.

LESSON 17
Bunching planner

Giving two or more years at once, in the year it’s worth most.

S-corp calculator

Salary, payroll costs and PTET, and the profit where it wins.

LESSON 23
QSBS checker

The five-year clock, the cap and stacking it.

LESSON 32

Also yours as a member

Bonuses

CPA

The CPA and filing rolodex

The CPAs and filing services I’d send a friend to, sorted by situation: a business, stock from work, a rental, two states, living abroad, a big sale.

STACK

My stack

Every tool I use for my own money, what it does for me and why I chose it. Anything I have a stake in or a role at is marked.

Partner bonus$250

$250 from Frec

When you open a direct indexing account through my referral link, the way the course harvests losses all year. Frec’s terms apply, shown before you open the account.

Partner bonus$500

Up to $500 from Carry

Carry matches what you put into a new Carry Solo 401(k), dollar for dollar up to $500, paid to you in cash, when you fund it by February 15, 2027. It takes a Lettuce Pro and a Carry membership, for the first 2,000 people. Carry’s terms.

I’m an investor in and adviser to Frec. I hold the title of strategic adviser at Lettuce Financial, which runs Carry’s Solo 401(k) platform. Each partner pays its own bonus, on its own terms.

Pricing

Less than one move is worth.

Get your number first, and your price is $299 for 7 days. Three questions, about two minutes.Find my number

Pay Less in Taxes

The course and the software that does it.

$499a year

One payment for the year, about $42 a month.

  • All 38 lessons, and the year’s new ones every January
  • All 29 tools and trackers
  • Your return read, Ask and What if, on your own year
  • The December email
  • The CPA and filing rolodex
  • $250 from Frec and up to $500 from Carry
  • My stack: every tool I use

Nothing renews unless you tick the box.

Pro

Your tax year, handed to your AI assistant and your accountant.

$999a year

Opens once all three are built.

  • Everything in Pay Less in Taxes
  • Reimburse inside Claude, ChatGPT and other AI assistants, running what-ifs on your own year
  • The CPA packet: your year, every move and the paper behind it, in one file for your accountant
  • Your return, checked before you sign: what’s missing from what you planned
Join the waitlist

If it doesn’t find you $499 in 30 days, it’s free.

Put in your pay stub or last year’s return and let Reimburse work out your year. If it doesn’t find at least what you paid in tax savings, on your own numbers, in your first 30 days, write to us and we’ll refund you in full. To claim, write to hello@reimburse.com within 30 days of joining and we’ll refund the full amount to your card. The app shows what it found, so there’s nothing to argue about.

Honestly

Who this is for, and who it isn’t

It’s for you if

You pay more than about $30,000 a year in tax, from a paycheck, a business or both.

You’ve heard of the backdoor Roth or tax-loss harvesting and haven’t done them.

You’d rather do this yourself with good tools than pay an adviser 1% of everything every year.

It isn’t for you if

You want someone to file your return. Reimburse doesn’t file; it gets the year right before anyone does.

You want tricks. No Augusta rule, no heavy SUV for the write-off, no insurance company of your own that never pays a claim. Every lesson cites the law it rests on.

Most of your tax comes out of one paycheck and you don’t have savings yet. Start with the free tools.

Questions

Frequently asked

Is that really you in the lessons?

I write and check every lesson. On camera is my digital twin, made with HeyGen, speaking in my cloned voice, and every lesson says so. That’s what lets us re-record a lesson the week a limit changes, so you’re never watching last year’s numbers.

Is this tax advice?

No. It’s education, and software that works out your own numbers from what you give it. For a decision with a lot riding on it, the course tells you what to ask a CPA, and the rolodex lists CPAs who fit your situation.

I already have an accountant.

Keep them. You’ll bring a year that’s already worked out, the moves you made and the paper behind them, which makes their hour cheaper and better.

I only have a W-2. Is there enough for me?

Start here, A paycheck and Investing were written for you: your benefits, the 401(k) past the match, the HSA, both backdoor Roths, RSUs, cash, gains and Roth conversions.

Why yearly?

Because the law and the limits change every year. Members get the year’s lessons and figures each January.

What are the partner bonuses?

Frec pays $250 when you open a direct indexing account through my referral link. Carry matches what you put into a new Carry Solo 401(k), dollar for dollar up to $500 in cash, when you fund it by February 15, 2027. Each pays its own bonus on its own terms, shown before you open the account. I’m an investor in and adviser to Frec, and I hold the title of strategic adviser at Lettuce Financial, which runs Carry’s Solo 401(k) platform.

What’s Pro?

Everything in the membership, plus three things that take your year out of Reimburse to where you need it: Reimburse inside your AI assistant, a packet for your accountant, and a check of your drafted return before you sign it. It opens once all three are built.

Two ways this goes

There are 67 days left in 2026.

You can close this tab. Nothing bad happens. You’ll pay about what you paid last year, and in March your accountant will tell you what it was.

Or you can spend an evening this week. Watch the lessons everyone starts with, put in your last pay stub, and see what’s in your plan.

Join for $499 a year
Ankur
AnkurAnkur Nagpal, founder of Carry and Teachable

P.S. If you do one thing this year, check where your next dollar should go. That tool is free: the savings waterfall.

P.P.S. I learned about QSBS two months before it would have been too late. I’d like you to find out about yours with more time than that.